
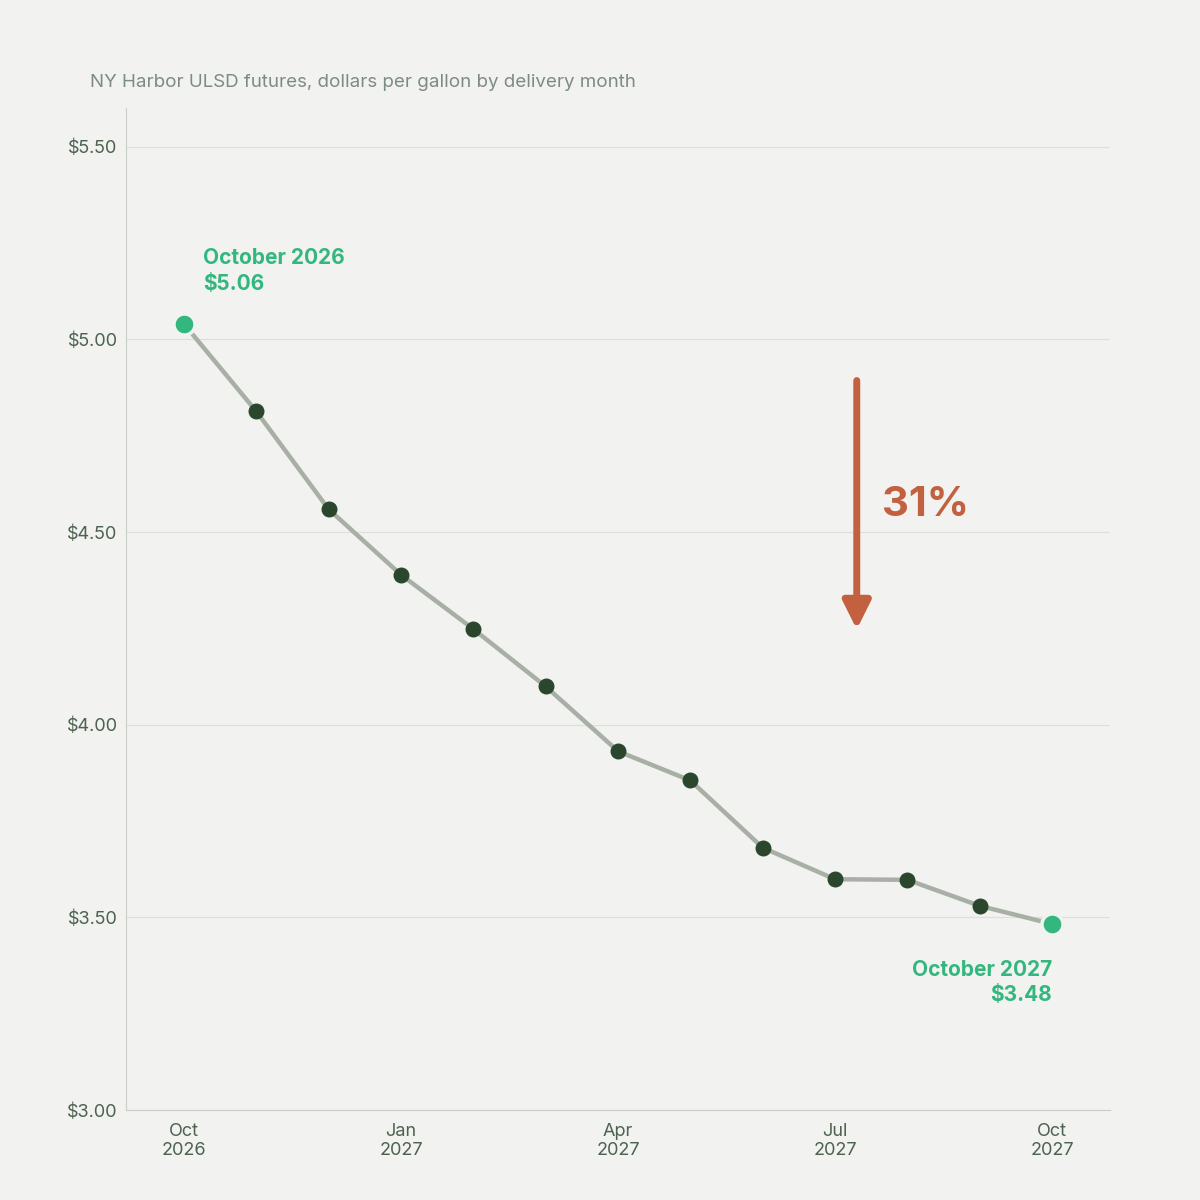
The diesel curve implies both wars end within a year
Download this chart with sources —>
Discuss this issue on LinkedIn —>
The NY Harbor ULSD contract for delivery next October is priced 31% below the contract for next month — $5.06 against $3.48. Carried to the pump, holding taxes and margins constant, that is $6.53 today against roughly $4.95.
The last distillate squeeze, in 2022, took two and a half years to clear, and it cleared two ways unavailable now: Russian barrels rerouted, and 1.5 million b/d of new refining capacity came online. That leaves demand destruction, and demand has not moved — US distillate consumption ran flat through the summer while retail diesel rose 43%.
Crude priced the same trajectory all year. In March, Brent traded just above $100 and the curve priced $88 six months out. Today Brent trades just below $100 and the curve prices $88 six months out.
Twenty years of watching forward curves and they price wars ending early far more often than late.
ULSD at $3.48 needs Hormuz open, Russian refining repaired, and roughly 1.5 million b/d of capacity back — inside twelve months. Which of those looks close, and what's missing from that list?
Method
Futures quotes are NYMEX New York Harbor ULSD and ICE Brent as of 22 September 2026. Settlement prices should be taken from CME Group and ICE directly; the figures here were captured from delayed quote services and may differ from official settlements by small amounts.
The pump-price conversion assumes fuel taxes and distribution margins hold constant. They will not hold exactly. It is offered as an order of magnitude, not a forecast of retail price.
One figure is single-sourced. The 18 March 2026 Brent curve, including the $88.21 September contract, comes from one trade publication and could not be cross-checked. The September figures cross-check across three independent sources.
Storage capacity is unmeasured. The EIA discontinued its Working and Net Available Shell Storage Capacity report; the last data is dated 31 March 2024. Any statement about spare tankage in this market is an estimate, including everyone else's.
No well-identified, recent, US-specific short-run price elasticity of demand for distillate exists in the published literature. The trucking estimates cited are sector-specific and are the closest available.
Sources
CME Group — NYMEX New York Harbor ULSD futures settlements
ICE — Brent crude futures settlements
EIA, Gasoline and Diesel Fuel Update — retail diesel $6.529/gal, 21 September 2026
EIA, Weekly Petroleum Status Report — inventories, refinery utilisation, exports
EIA, Weekly Product Supplied of Distillate Fuel Oil (WDIUPUS2)
EIA, Refinery Capacity Report
Congressional Research Service, "Diesel and Fuel Oil: Distillate Supply Issues" (R47469)
Winebrake, Green, Comer & Li, "Fuel price elasticities in the U.S. combination trucking sector," Transportation Research Part D 38 (2015)
DAT Freight & Analytics, August 2026 rate release
American Farm Bureau Federation, "Diesel Prices Surge as Global Supplies Tighten," 17 September 2026
Business Standard, "India emerges as key diesel supplier to Europe," 6 September 2026
IEEFA — Europe to source two-thirds of its LNG imports from the US in 2026
Euronews, "EU fuel prices hit records," 19 September 2026